Why the annual fee on your card keeps rising
Wondering why your credit card’s annual fee keeps climbing? Discover the reasons behind these hikes and find out how to determine if your card still offers good value.
Is your credit card becoming costly? Keep an eye on the annual fee
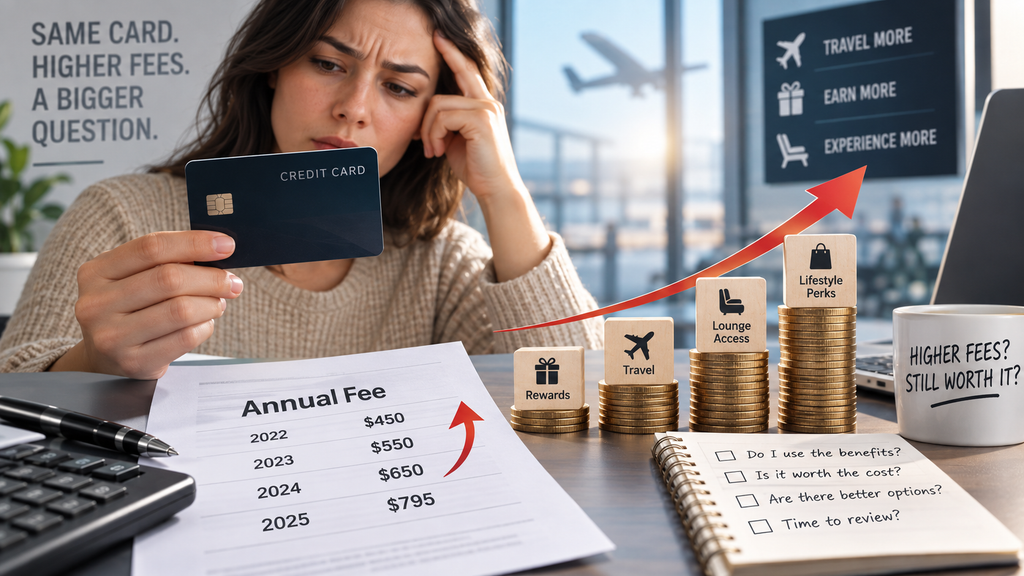
Your credit card’s annual fee might continue to rise as issuers hike prices for premium rewards, introduce more travel and lifestyle perks, tweak card economics, and shift their focus toward customers who spend more.
A bigger annual fee doesn’t always mean your card is a better or worse value.
The main consideration is whether the perks you actually use outweigh the increased fee.
What’s Driving Up My Credit Card’s Annual Fee?
A credit card annual fee may rise if the issuer updates the card’s pricing structure or modifies its benefits.
Premium cards have increasingly added travel credits, lounge access, rewards, and lifestyle perks, often alongside higher annual fees.
For instance, recent updates to premium cards have driven some annual fees close to or beyond $800 per year.
The key difference lies between the value promoted by the issuer and the actual benefits you gain personally.
What Causes Credit Card Annual Fees to Go Up?
Common reasons include the following:
- New travel credits added
- Broader airport lounge access
- Increased rewards rates
- Additional hotel or dining perks
- More statement credits
- Updates to the rewards program
- Higher expenses tied to premium rewards
- Card repositioned for bigger spenders
Are Annual Fees on Credit Cards Increasing Industry-Wide?
Fee hikes have been especially notable among premium credit cards.
The Federal Reserve Bank of New York noted that U.S. credit card debt hit $1.26 trillion in Q2 2026, underscoring credit cards’ ongoing role in household budgets.
At the higher end of the market, some credit cards now carry annual fees in the several hundreds, with a few products nearing or topping $800 per year.
What Drives Premium Credit Cards to Increase Their Annual Fees?
These premium cards are increasingly competing by bundling together a variety of travel and lifestyle perks.
So, a higher annual fee often corresponds to a more costly package of benefits, though more perks don’t always translate to greater value for every cardholder.
Travel Credits Can Help Offset a Steep Annual Fee
Imagine a card that charges a $795 annual fee but includes $300 in travel credits.
The straightforward math looks like this: $795 − $300 = $495
However, that $300 credit only holds full value if you would have spent that amount on qualifying items anyway.
If you redeem only $150 of that credit, then its actual worth to you is about $150, not the full $300.
This difference is one of the key points to consider when assessing premium credit cards.
The Value of Airport Lounge Access Varies Among Different Travelers
Access to airport lounges can be quite beneficial for those who travel often.
If you fly multiple times a year, lounge access might replace expenses you’d otherwise incur at the airport.
But for those who travel infrequently, this perk may offer little real benefit.
Don’t judge a benefit by its listed price—assess it based on the actual savings it provides you.
Rewards Are Only Worthwhile When They Align With Your Spending Habits
A higher rewards rate can help balance out an annual fee if it applies to the purchases you already plan to make.
However, spending extra just to earn rewards usually defeats the original intent.
For instance, a card that gives bonus points on dining doesn’t justify racking up an unnecessary $500 restaurant bill as a way to save money.
Your rewards should be a result of your spending habits, not a reason to increase them.
Should You Keep Your Credit Card After Its Annual Fee Goes Up?
Before deciding to keep, switch, or cancel your card, it’s important to weigh several key factors.
Look at How It Compares to No-Fee Cards
Avoid limiting your comparison to just other premium cards.
Instead, evaluate its overall annual worth against a card with no yearly fee.
Check with Your Issuer About Switching Products
Before you close your account, see if your issuer offers the option to switch to a different card product.
Depending on your issuer and account type, you might be able to downgrade to a card with a lower or no annual fee.
Not all issuers provide this option.
Are Credit Card Companies Allowed to Increase Your Annual Fee?
In general, federal regulations allow increases in certain annual or monthly maintenance fees after the initial year, as long as the issuer meets the required conditions.
Regulation Z along with guidance from the CFPB sets specific notification rules for some credit card term changes.
Certain modifications require at least 45 days’ notice ahead of time, though the requirements vary depending on the type of change involved.
How Much Notice Does a Credit Card Issuer Have to Give?
When changes fall under Regulation Z, cardholders typically get advance notification before those changes take effect.
The notice should clearly outline key details such as:
- The updated fee
- The date the change begins
- Which account terms are affected
- Any rights or choices you have
Be sure to carefully review the issuer’s notice, as the rules can vary by fee type and account details.
Is It Possible to Avoid Paying a Credit Card Annual Fee?
In some cases, yes. You might consider options like:
- Switch to a no-fee card offered by the same issuer;
- Inquire about possible product changes;
- Evaluate how the card compares with other options;
- Contact the issuer to see if retention offers are available;
- Consider canceling the card, weighing credit score impacts.
Does Closing a Credit Card Lower Your Credit Score?
Shutting down a credit card may impact key components of your credit score.
An especially important factor to watch is credit utilization.
What Steps Should You Take If You Carry a Credit Card Balance?
If you carry a balance from month to month, the annual fee shouldn’t be your only worry.
The Federal Reserve Bank of New York noted that U.S. credit card debt hit $1.26 trillion in the second quarter of 2026.
For cardholders with revolving balances, the interest charges often outweigh any gains from maximizing rewards.
Should You Spend More to Offset an Annual Fee?
No budget calculation should be based on spending extra money you wouldn’t normally spend.
When a card’s annual fee is $500, adding thousands more in spending just to rack up rewards may actually raise your costs instead of lowering them.
The aim isn’t to earn enough rewards to make extra spending worthwhile.
Instead, the objective is to get the most value from the spending you were already going to do.
Author’s Perspective
A rising credit card annual fee calls for a fresh review, especially when the increase reaches several hundred dollars.
The important factor isn’t just whether the issuer added extra perks. It’s whether those perks fit your actual spending, travel habits, and card usage.
When you already take advantage of the credits and rewards, the higher fee might be balanced out by benefits you would have bought regardless.
If you don’t use those perks, the stated value can give a false impression of what the card actually costs you.
The easiest way to judge is: how much did I really save over the past year, and how much did the card cost me?
That calculation offers a clearer understanding than relying on the marketing value assigned to each benefit.
Also, if you carry a balance, keep in mind that optimizing rewards should come only after you fully understand your interest charges.
Recommended Content
Health insurance
Health insurance options may change. Learn why premiums could rise, insurers may exit markets and how to prepare.
Continue reading * You will remain on the current website